
On a freezing morning in Ann Arbor during his undergraduate years at the University of Michigan, Paul Milgrom opened his front door to sub-zero temperatures, looked at his schedule for an 8 a.m. physics class located far across campus, turned around, and climbed right back into bed. That decision according to his biographical account prompted Milgrom to drop the physics course and focus entirely on mathematics. It was one of several early pivots that redirected a career initially focused on insurance math toward fundamental theoretical breakthroughs in economics.
An Actuarial Start and an Early Pivot
Milgrom grew up in Oak Park, Michigan, where his interest in mathematics led him to attend the Ross summer math camp at Ohio State University in 1965, finishing first in his class. After graduating from the University of Michigan in 1970 with a Bachelor of Arts degree in mathematics, he took a job as an actuarial trainee at the Metropolitan Life Insurance Company in San Francisco. While preparing for actuarial exams during later stays in Ann Arbor and Columbus, Ohio, Milgrom published two prize-winning theoretical papers in the Transactions of the Society of Actuaries.
Seeking a broader understanding of business, Milgrom enrolled in the MBA program at Stanford University in 1975. His career trajectory shifted during an advanced methods class when Professor Evan Porteus asked about the rate at which an approximation converged. When Milgrom explained that the convergence rate depended on the subdominant eigenvalue of the Markov matrix, Porteus advised him to leave the MBA program and pursue a Ph.D. instead.
Finding the Right Adviser at Stanford
Milgrom accepted Porteus's advice but needed to select a dissertation topic and adviser. An advanced graduate student, Bengt Holmström, advised Milgrom to seek out Robert Wilson as his dissertation adviser. Milgrom enrolled in Wilson’s course on multi-person decision theory and wrote a term paper that extended Wilson’s existing research on common-value auctions.
In his paper, Milgrom derived the necessary and sufficient conditions for an auction's winning price to show convergence-in-probability toward the true underlying value of the asset as the number of bidders grew large. Wilson recognized the strength of the mathematical proof and told Milgrom the paper could form the core chapter of his doctoral dissertation. Milgrom completed his Ph.D. in 1978, and Stanford officially awarded the degree in 1979. The term paper was published in 1979 as Milgrom's first economics paper.
Bringing Incomplete Information to Economics
After completing his doctorate, Milgrom accepted his first academic faculty appointment at Northwestern University's Kellogg School of Management. In Evanston, he collaborated with researchers including Bengt Holmström, Roger Myerson, John Roberts, and Robert Weber. The group focused on integrating game theory with incomplete information into core economic models, an approach that faced significant initial resistance from economists who argued that competitive modeling should rely solely on physical supply, demand, and market entry barriers.
In 1982, Milgrom and Roberts published papers demonstrating how incumbent firms use limit pricing and predatory pricing to influence the beliefs of potential market entrants. By showing that low pricing could signal aggressive future competition to competitors, their models proved that information structures and beliefs directly shaped observable industrial outcomes.
The No-Trade Theorem and Modern Auction Theory
In 1982, Milgrom and Nancy Stokey introduced the Milgrom-Stokey No-Trade Theorem. The theorem proved that risk-averse economic agents will not engage in speculative trading based purely on differences in private information. Because rational traders infer that an opponent taking the other side of a trade possesses information that renders the deal disadvantageous, net speculative trade cannot occur without transactional motives such as liquidity needs.
That same year, Milgrom and Robert Weber published a generalized auction model that combined the earlier framework of William Vickrey with Wilson's common-value model. The Milgrom-Weber analysis formulated the linkage principle, demonstrating that disclosing public information about an item's value reduces the winner's curse for bidders and systematically raises the seller's expected revenue across various auction formats.
Milgrom’s early theoretical work on information structures later formed the foundation for practical market applications, including the radio spectrum auctions conducted by the Federal Communications Commission in the 1990s. In 2020, Milgrom was awarded the Nobel Memorial Prize in Economic Sciences alongside Robert Wilson for their improvements to auction theory and inventions of new auction formats.
Cover: AI-generated editorial illustration; not a documentary photograph.
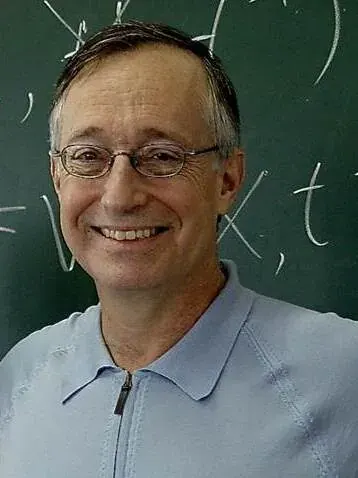
Source: Nobel Prize
Paul R. Milgrom
 SIGNAL TITANS

Leave a Reply